LST Depegs: Why stETH Traded Below ETH and What It Meant
The discount was never a backing failure. It was a liquidity event in an asset that could not be redeemed at the time.
Nadia OkoroPolicy & Consumer Editor · Regulation, tax, stablecoins and the products retail users holdUpdated 4 October 2026
The short answer
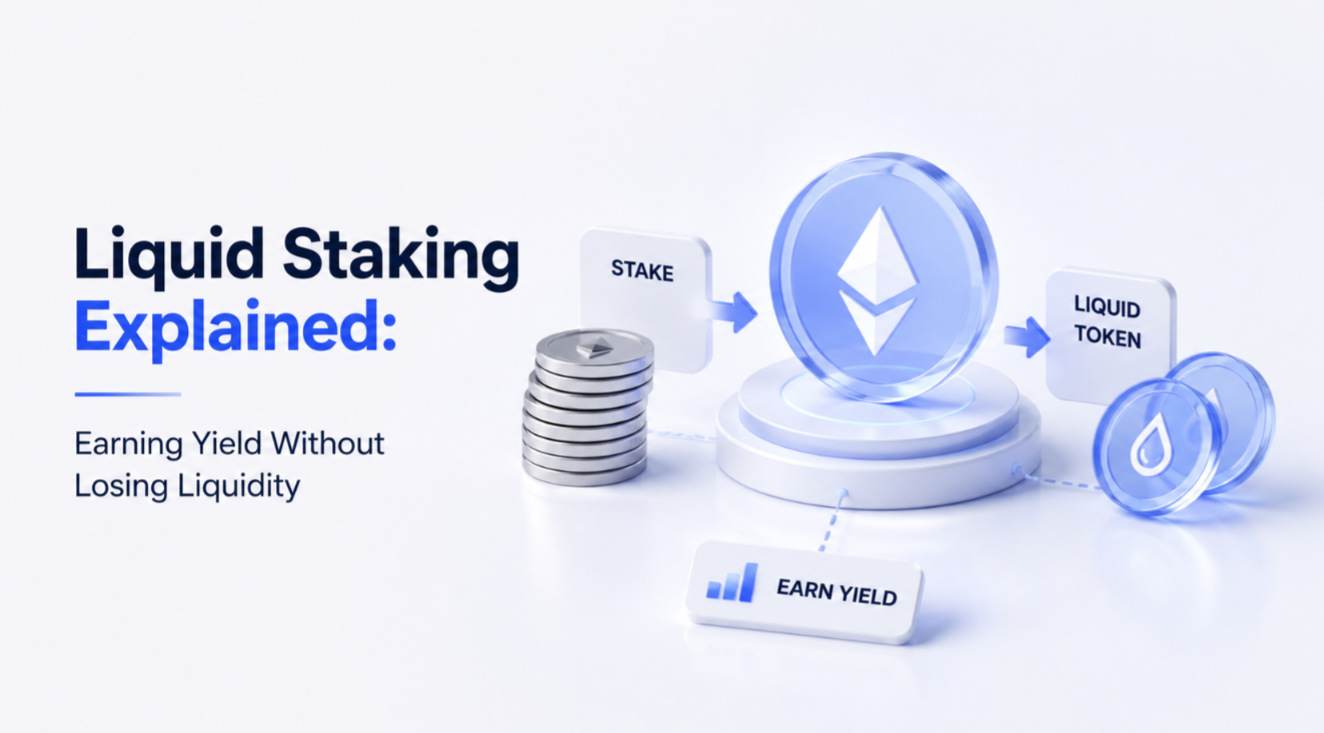
A liquid staking token represents staked ETH plus rewards, redeemable for ETH through the network's exit queue. Before withdrawals were enabled in April 2023, that redemption did not exist, so the token's price depended entirely on secondary market liquidity — and in June 2022 forced selling by leveraged holders pushed stETH several per cent below ETH. Withdrawals now provide an arbitrage anchor, but discounts can still open when exit queues lengthen or leveraged positions unwind.
In June 2022, stETH traded roughly 5% below ETH, and a large part of the market read it as a solvency question about Lido. It was not. Every stETH was backed by staked ETH the entire time. What did not exist was a way to get that ETH out.
What an LST actually is
A liquid staking token is a claim on staked ETH plus accrued rewards. Its exchange rate against ETH is set by the protocol from the underlying balance — it grows as rewards accrue, and it is not a peg in the stablecoin sense.
The market price is a separate thing. It is whatever someone will pay right now, and it converges to the exchange rate only if there is a reliable way to convert one into the other. That mechanism is redemption, and its availability is the whole story.
Why the 2022 discount opened
Ethereum's transition to proof of stake had happened conceptually but withdrawals were not yet live. Staked ETH was locked with no exit date, so stETH holders wanting ETH had exactly one option: sell in the secondary market.
At the same time, a large share of stETH was held in leveraged loops — borrow ETH against stETH, buy more stETH, repeat. When prices fell, those positions faced liquidation, and unwinding required selling stETH into a market where the only buyers were people willing to hold an illiquid claim indefinitely. Celsius held a very large stETH position it could not exit; Three Arrows and others were unwinding simultaneously.
The result was a classic forced-seller discount: a solvent asset trading below its intrinsic value because the marginal seller had no choice and the marginal buyer had no deadline.
What changed with withdrawals
The Shapella upgrade in April 2023 enabled staked ETH withdrawals. This changed the structure permanently, because an arbitrage now exists: if stETH trades below ETH, someone can buy stETH, redeem it through the exit queue, and receive ETH worth more than they paid.
That arbitrage is not instant — it takes as long as the exit queue takes — so the discount does not close immediately. It becomes a function of the queue: a two-day queue supports a discount of a few basis points, a three-week queue supports considerably more. The mechanics of that queue are covered in withdrawal queues.
When discounts can still open
Three scenarios, all of which have appeared since.
**Queue congestion.** Mass exits lengthen the wait, widening the discount the arbitrage can tolerate. This is self-reinforcing: a discount encourages more people to sell rather than queue, and heavy exit demand lengthens the queue further.
**Leverage unwinds.** The loop trade never went away. It is now a standard strategy on major lending markets, and it still means that a fall in ETH forces stETH selling into a market that widens exactly when it is needed most.
**Smaller LSTs.** The arbitrage requires liquidity to execute and a redemption path that works. A minor liquid staking token with thin pools can trade at a persistent discount because nobody is doing the trade, and one with an operator-controlled redemption process may not have the path at all.
What a discount does and does not tell you
It is a liquidity signal, not a backing signal. To check backing, look at the protocol's reported total staked ETH against the token supply and at the exchange rate's continued accrual — both are on-chain and verifiable.
The genuine solvency risks in an LST are different: validator slashing reducing the underlying balance, node operator concentration, the withdrawal credential setup, and the governance of the contracts. Those risks would show up as a change in the exchange rate, not as a market discount, and they are what the liquid staking ratings weight most heavily.
The practical lessons
First, the LST discount is priced by the exit path, so know what yours is: redemption available on demand, redemption through a queue of some length, or no redemption at all.
Second, do not lever a position whose collateral is the asset you would need to sell in a stress event. The loop trade is profitable most of the time and mathematically designed to fail at the moment everyone needs to exit.
Third, protocols pricing LST collateral at the underlying exchange rate rather than the market price protect borrowers from exactly this scenario — and that oracle choice, listed in the protocol documentation, is worth checking before you borrow against one.
Fourth, if you are holding an LST for staking yield rather than for liquidity, a discount is an opportunity rather than an event. The redemption still pays the full underlying amount whenever the queue clears.
FAQ
Why did stETH trade below ETH?+
Before withdrawals were enabled in April 2023, staked ETH could not be redeemed, so stETH holders wanting ETH had to sell in the secondary market. Forced selling from leveraged positions in June 2022 pushed the price several per cent below ETH.
Is a liquid staking token pegged to ETH?+
No. It is a claim on staked ETH plus rewards, with an exchange rate set by the protocol. The market price converges to that rate only to the extent redemption is available and quick.
Can stETH depeg again?+
A discount can open whenever the exit queue lengthens or leveraged positions unwind, because the arbitrage takes as long as the queue takes. It reflects liquidity, not a failure of backing.
How do I check that an LST is fully backed?+
Compare the protocol's reported staked balance against token supply on-chain and confirm the exchange rate is still accruing. Backing problems appear in the exchange rate, not in the market discount.
 Nadia OkoroPolicy & Consumer Editor · Regulation, tax, stablecoins and the products retail users hold