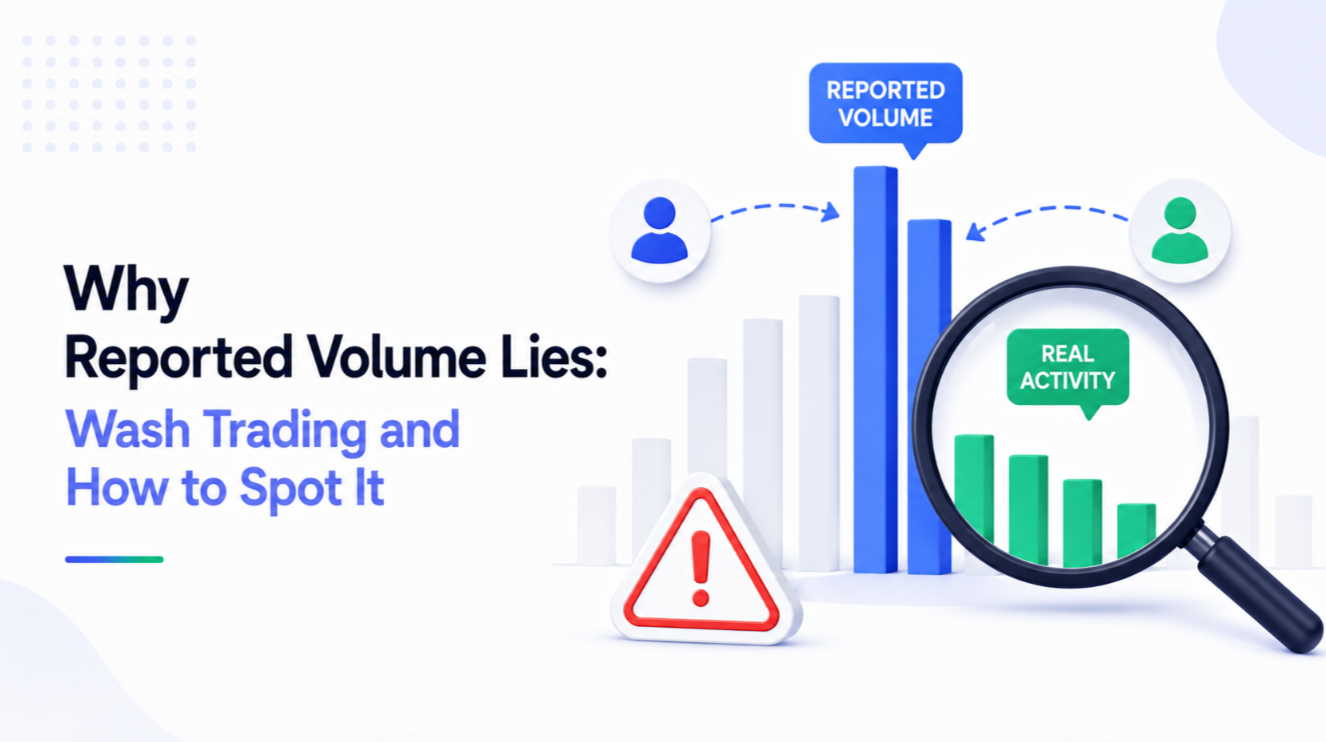
Wash trading is buying and selling with yourself to create the appearance of activity. Exchanges report their own volume with no independent verification, and rankings, listings and marketing budgets all key off it. The reliable fingerprints are volume out of proportion to order book depth, round-number trade sizes, uniform timing, traffic that does not match reported turnover, and volume that does not move the price. Depth and spread are harder to fake and better measures.
- 1Why anyone bothers. Four incentives, each sufficient on its own.
- 2Fingerprint one: volume that does not fit the book. The strongest single test.
- 3Fingerprint two: the shape of the trades. Real order flow is messy.
- 4Fingerprint three: volume without price movement. Genuine buying and selling has price impact.
On this page7 sections
Every exchange reports its own volume. No one verifies it. Aggregators publish it, rankings sort by it, projects choose listings by it, and market makers are hired against it — a self-reported number sitting under a large part of the industry's decision-making.
Academic and regulatory studies of unregulated venues have repeatedly found that the majority of reported spot volume on some exchanges does not correspond to genuine economic trading. The exact proportion is contested; that a large share is fabricated is not.
Why anyone bothers
Four incentives, each sufficient on its own. Ranking position on aggregator sites drives user acquisition, and the ranking is sorted by volume. Projects pay listing fees to venues with apparent liquidity. Token teams want their asset to look tradable, which sustains a market for wash trading as a service. And on NFT marketplaces with token incentives, trading against yourself has been directly profitable — the reward for volume exceeded the fee paid to generate it.
The last case is the cleanest illustration, because it needs no deception at all: if a platform pays users to trade, users will trade with themselves until the payment stops.
Fingerprint one: volume that does not fit the book
The strongest single test. Genuine turnover requires liquidity to trade against. If a venue reports enormous daily volume in a pair whose order book shows thin depth within 1% of mid, the two facts are incompatible — you cannot move that size through that book without moving the price far more than it moved.
Compute the ratio: reported 24-hour volume divided by the sum of bids and asks within 2% of mid. Compare across venues for the same pair. Outliers of an order of magnitude are not efficiency.
Fingerprint two: the shape of the trades
Real order flow is messy. Trade sizes cluster around human and algorithmic conventions but scatter widely, and inter-arrival times follow a bursty, heavy-tailed pattern.
Fabricated flow tends to be regular. Round sizes — exactly 1.0, exactly 0.5 — appearing far more often than in a normal distribution. Trades arriving at suspiciously even intervals. A first-digit distribution across trade sizes that departs from what naturally occurring numbers produce. None of these is proof alone; together on one venue they are close to it.
Fingerprint three: volume without price movement
Genuine buying and selling has price impact. If a pair reports substantial turnover with a price that barely moves and a spread that never widens, the trading is not consuming liquidity — which usually means the same party is on both sides.
The inverse also flags: a price that moves violently on tiny genuine volume is a thin market, which is a different problem but equally relevant if you plan to exit.
Fingerprint four: activity that does not match the business
Cross-check reported turnover against independent signals of a real user base — web traffic, app installs, engagement, the number of distinct addresses depositing and withdrawing on-chain. A venue reporting volume comparable to a top-five exchange while attracting a fraction of the traffic is describing users who do not exist.
For on-chain marketplaces this is easier, because settlement is public: look for assets repeatedly sold between a small set of addresses funded from the same source, at rising prices, with no third party ever entering. Wash trading on-chain leaves a permanent record and is the reason NFT volume figures require heavy filtering before use, which the better analytics tools apply explicitly.
What to measure instead
Depth is harder to fake because it is capital at risk: to show real bids, someone must post them and accept being filled. Measure the size available within 0.5% and 2% of mid, at several times of day.
Spread persistence tells you whether the depth is real. A market maker will widen in volatility; a fake book often does not, because nothing is genuinely at risk.
Slippage on a test trade is the honest measure. Execute a realistic size and compare the fill against the quote. This costs a small amount and settles the question completely.
And for custodial venues, verifiable reserves and withdrawal reliability matter more than any activity metric — a venue with genuine volume that cannot process withdrawals has failed at the only thing that counted. That is why our exchange ratings score liquidity from observed depth and spread rather than reported volume, and why the methodology states which figures are self-reported wherever they appear.
The habit to carry
Treat every volume figure as a claim by an interested party until you have checked it against something that costs money to fake. Depth costs money. Traffic costs money. Volume, on a venue that reports its own, costs nothing.
Next step
Understood the mechanics? Keep going, or compare the services.
FAQ
What is wash trading in crypto?
How can I tell if an exchange's volume is fake?
Why do exchanges inflate volume?
What is a better measure than volume?
Related guides
All Trading & exchanges guides →- Maker-Taker Fees: The Number Exchanges Don't AdvertiseThe headline fee on an exchange's marketing page is the maker rate at a volume tier you will never reach. Here is what you actually pay.Beginner8 min
- How Automated Market Makers (AMMs) Work Under the HoodNo order book, no market makers standing by — just a formula and a pool of reserves. Here's the mechanics behind the constant-product curve that prices most of DeFi.Intermediate10 min
- Order Book Depth: Reading the Number That Sets Your FillPrice is what the last trade happened at. Depth is what your trade will happen at, and the two are only similar in liquid markets.Beginner7 min
- Perpetual Futures Explained: How Crypto Derivatives WorkPerpetual futures now trade several multiples of spot crypto volume most days. Understanding how perps and funding rates actually work is the difference between using leverage deliberately and being liquidated by it.Intermediate12 min