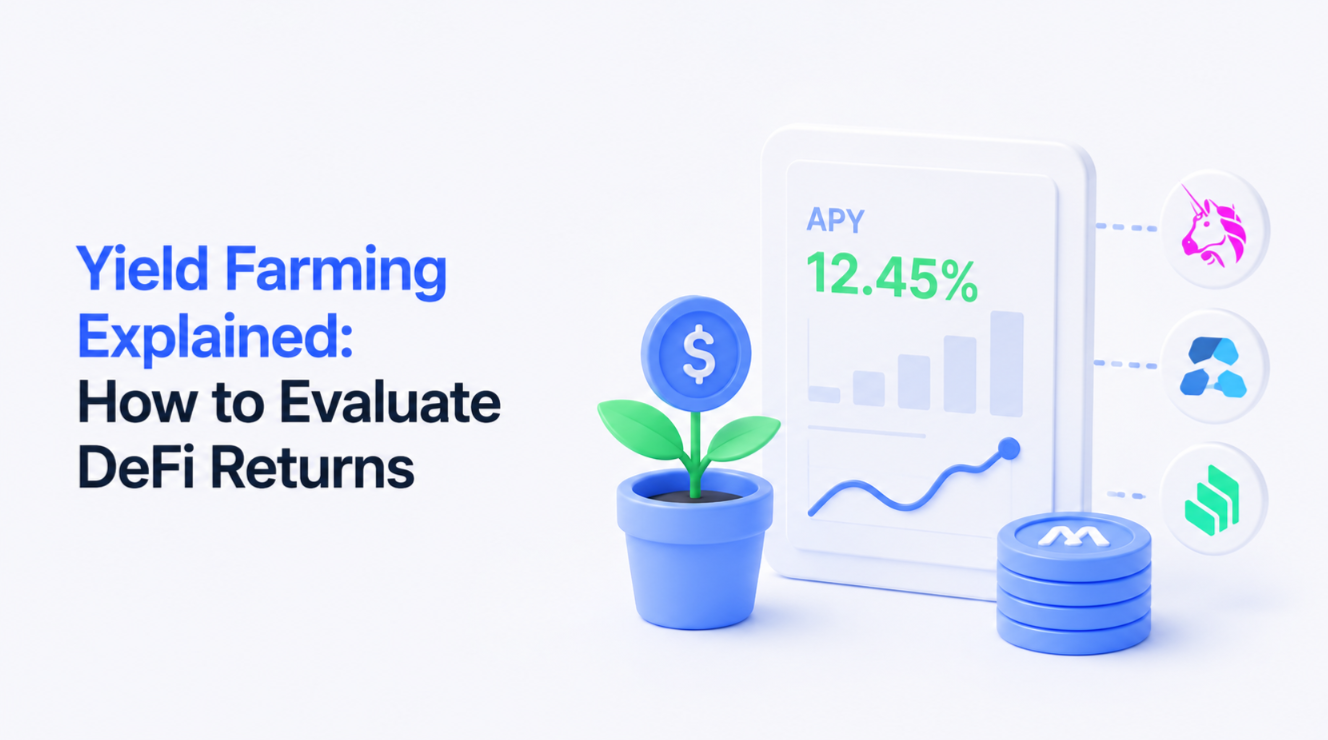
Yield farming deploys capital into DeFi for returns from fees, interest and token incentives. The skill is not finding the highest advertised number but splitting it into base yield, funded by real revenue and durable, and emissions, funded by dilution and temporary. Displayed rates also annualise short windows and exclude fees, gas, impermanent loss and the slippage of selling rewards.
- 1What Yield Farming Actually Is. Strip away the branding and yield farming is just liquidity provision with a rewards layer bolted on.
- 2Where the Yield Actually Comes From. There are really only three sources of yield in DeFi, and it matters enormously which one you're being paid from.
- 3The Emissions Trap. Emission-driven yield isn't inherently a scam, but it is inherently temporary, and the mechanics work against latecomers.
- 4A Framework for Evaluating Real Yield. Before farming anything, check three numbers.
On this page7 sections
Yield farming has produced some of the most spectacular returns in crypto and some of the most spectacular wipeouts, often in the same protocol within the same quarter. The pitch is always the same: deposit assets, receive a headline APY that would make a hedge fund manager blush, collect rewards. What the pitch rarely explains is where that yield originates, and that omission is the single most useful thing to interrogate before you commit capital.
What Yield Farming Actually Is
Strip away the branding and yield farming is just liquidity provision with a rewards layer bolted on. You deposit two assets into an automated market maker pool, or a single asset into a lending market, and you receive a receipt token representing your share. Protocols then layer additional incentives on top, usually paid in their own governance token, to attract deposits faster than organic demand would. The receipt token itself can often be restaked or supplied elsewhere, which is how a single deposit ends up generating three or four overlapping reward streams and an APY figure north of 100%.
Where the Yield Actually Comes From
There are really only three sources of yield in DeFi, and it matters enormously which one you're being paid from. The first is trading fees, a genuine cut of swap volume passing through a pool, funded by actual users doing actual trades. The second is protocol revenue, such as a lending market's interest spread or a perpetuals exchange's funding fees, which reflects real economic activity. The third is token emissions, newly minted governance tokens handed out as an incentive, which cost the protocol nothing today but dilute every existing holder tomorrow.
Trading Fees vs Emissions
Take a concrete example. A stablecoin pool on a mid-tier AMM might show a 6% APY built entirely from swap fees, funded by arbitrageurs and traders moving capital through the pool. That yield is real and roughly durable, moving with volume rather than vanishing on a schedule. Compare that with a new farm advertising 400% APY on a freshly launched token pair, where the entirety of that figure comes from emissions of the protocol's own token. The fee component might be 2%. The other 398 points are the protocol printing IOUs against its own future.
The Emissions Trap
Emission-driven yield isn't inherently a scam, but it is inherently temporary, and the mechanics work against latecomers. Early farmers receive tokens when few people are claiming and the token's price hasn't been tested by sell pressure. As the farm attracts more capital chasing the advertised APY, the same emission budget gets split across more depositors, so the realised return per dollar falls even before price movement is considered. Meanwhile farmers who received tokens early are selling into the market to realise profit, pushing the token price down, which lowers the dollar-denominated APY further and accelerates the next wave of selling. This is the death spiral pattern that killed dozens of high-APY farms across 2021 and 2022, and it recurs on every cycle because the mechanics haven't changed, only the branding.
A Framework for Evaluating Real Yield
Before farming anything, check three numbers. First, compare total value locked against fully diluted valuation of the reward token: a farm with $10m TVL rewarding a token with a $500m FDV is promising future dilution at a scale that dwarfs current deposits. Second, find the emission schedule and work out what percentage of circulating supply is being minted weekly; anything above low single digits is aggressive and will show up as sell pressure fast. Third, ask where protocol fees actually go. If real revenue is distributed to token holders or used to buy back and burn supply, the token has a claim on cash flow independent of the farm. If fees vanish into a treasury with no distribution mechanism, the token's only source of demand is speculation on the farm continuing to attract new deposits, which is a much shakier foundation.
Impermanent Loss Is Not Optional
Every two-sided liquidity position carries impermanent loss, the gap between holding two assets separately versus holding them inside a pool that automatically rebalances as prices move. If you provide equal value of ETH and a volatile altcoin, and the altcoin doubles against ETH, the pool's constant-product formula has sold some of your altcoin into ETH along the way, leaving you with less upside than simply holding both assets would have given you. On a 2x relative price move, impermanent loss versus holding is roughly 5.7%; on a 5x move it's closer to 25%. Farming rewards need to outpace this drag, and on volatile pairs they frequently don't once the emission APY normalises.
Concentrated Liquidity Adds Another Layer
Uniswap v3-style pools let you concentrate capital into a price range to boost fee capture, which can multiply effective yield several times over for the same deposit. It also multiplies impermanent loss and introduces a new failure mode: if price exits your chosen range, your position stops earning fees entirely and sits as a single, fully exposed asset until price returns or you manually rebalance. Concentrated liquidity rewards active management and punishes the set-and-forget approach that worked reasonably well on older constant-product pools.
Practical Checklist Before Farming
Work through this before depositing: is the majority of the advertised APY coming from fees/revenue or from emissions? What is the emission token's FDV relative to pool TVL? Has the contract been audited, and by whom? Is there a lock-up or vesting schedule on emitted rewards, or can farmers dump immediately? What happens to your position if one side of the pair collapses to zero? And critically, what is your actual break-even time once impermanent loss and gas costs across multiple chains are netted out?
The Bottom Line
Sustainable yield in DeFi looks unglamorous: mid-single-digit to low-double-digit returns backed by fees or revenue that would exist whether or not a rewards programme was running on top. Unsustainable yield looks spectacular for exactly as long as new deposits keep arriving faster than early farmers cash out, and then it doesn't. The skill in yield farming isn't finding the highest number on the leaderboard, it's correctly pricing how much of that number is real economic activity and how much is a countdown timer on token dilution.
Next step
Understood the mechanics? Keep going, or compare the services.

FAQ
What is yield farming?
How do I tell sustainable yield from emissions?
Why is my actual return lower than the advertised APY?
What should I check before farming?
Related guides
All DeFi guides →- APR vs APY vs Real Yield: Reading a Rate HonestlyThe number on the dashboard is annualised from a recent window, before fees, and often paid in a token whose price is falling. Here is how to get to the real one.Beginner8 min
- What Is DeFi? A Beginner's Guide to Decentralized FinanceA first-principles map of decentralized finance — the building blocks, the big protocol categories, and the honest risks — before you send a single transaction.Beginner10 min
- Yield-Bearing Stablecoins: Where the Yield Comes FromA dollar that pays you something is a dollar taking a risk on your behalf. The only question worth asking is which one.Intermediate10 min
- Impermanent Loss Explained: The Hidden Risk of Providing LiquidityProviding liquidity looks like free yield until you compare it against simply holding the two assets — the gap between those outcomes is impermanent loss, and it's bigger than most LPs realise.Intermediate11 min