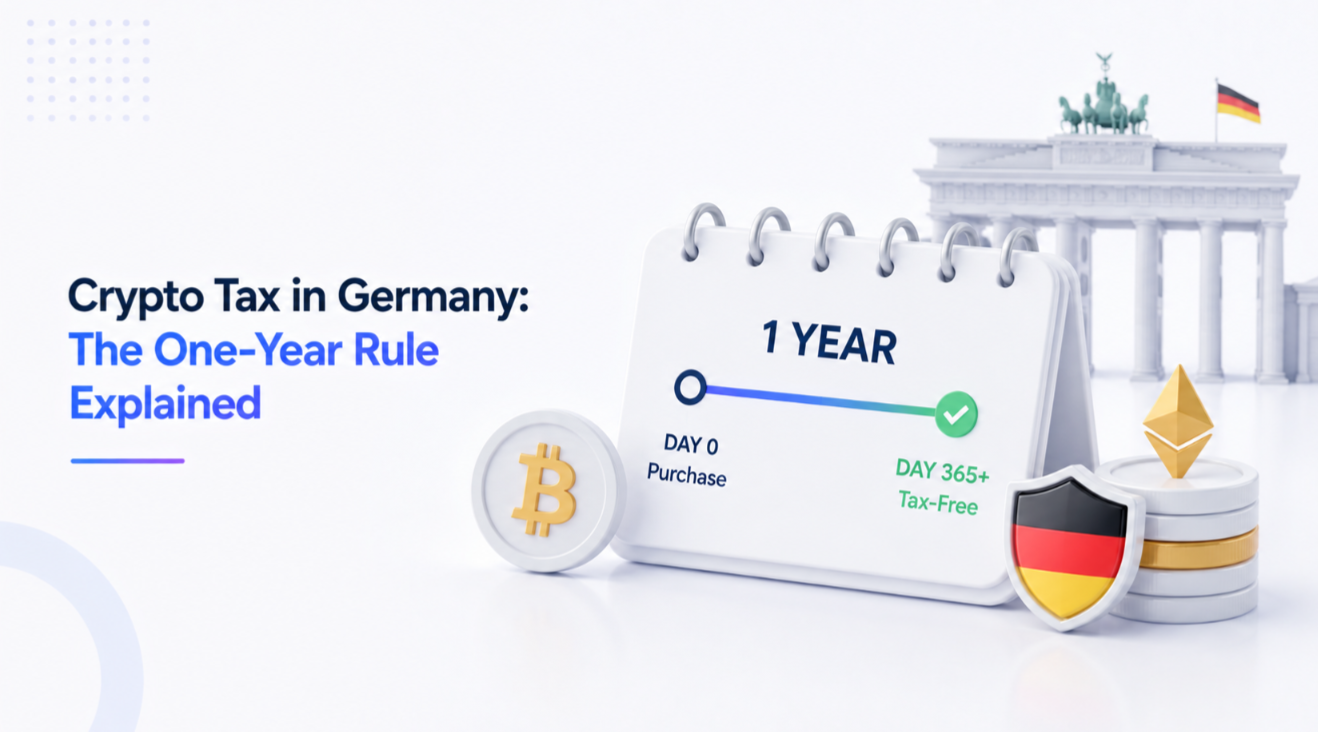
Germany treats cryptoassets held privately as other assets under §23 EStG. Disposals within one year of acquisition are private sale transactions taxed at your personal income rate, subject to an exemption limit; disposals after more than one year are generally tax-free. Staking and lending rewards are usually taxable as income at receipt. Trading at a scale that becomes commercial activity leaves the private regime entirely. This is general information, not tax advice.
- 1The one-year holding period. Buy a token, sell it within a year, and the gain is a private sale transaction taxed at your personal income tax rate.
- 2What counts as a disposal. The same broad set as elsewhere: selling for euros, swapping one token for another, and spending crypto on goods or services.
- 3Staking, lending and the income side. Rewards from staking, [lending](/ratings/lending/) and similar activity are generally taxable as income when received, valued in euros at that…
- 4Private versus commercial. The whole favourable framework applies to private asset management.
On this page7 sections
Germany's crypto tax framework is not a special crypto regime. It is the long-standing treatment of private sales of other assets — §23 of the Einkommensteuergesetz — applied to tokens, and it produces an outcome no other major economy matches: hold for more than a year and the gain is generally not taxed at all.
This is general information about how the rules are structured. German tax is fact-specific and the classification questions below are where cases turn, so a Steuerberater with crypto experience is worth engaging for anything material.
The one-year holding period
Buy a token, sell it within a year, and the gain is a private sale transaction taxed at your personal income tax rate. Sell it after more than a year and it falls outside the taxable window.
Two details do the work. The period runs from acquisition to disposal on a per-unit basis, so what matters is which units you are deemed to have sold — Germany generally uses FIFO per wallet, meaning the oldest units go first, which is usually favourable because they are the ones most likely to have passed the year.
And there is an annual exemption limit for total gains from private sales within the year. Below it, nothing is due; exceed it and the whole amount becomes taxable, not just the excess. Losses from private sales offset gains from private sales, and are carried where they cannot be used.
What counts as a disposal
The same broad set as elsewhere: selling for euros, swapping one token for another, and spending crypto on goods or services. A crypto-to-crypto swap starts a new holding period for the token received and ends the one for the token given up.
This is what makes active trading expensive in Germany and passive holding cheap. Every rebalance resets a clock. A portfolio traded monthly never accumulates a single tax-free position, and the crypto card problem is the same: spending from a volatile balance is a stream of disposals inside the window.
Staking, lending and the income side
Rewards from staking, lending and similar activity are generally taxable as income when received, valued in euros at that moment, under the rules for other income rather than as private sales. That receipt value becomes the acquisition cost for the tokens, and their own one-year clock starts then.
The German treatment here has moved over time. An earlier position extended the holding period to ten years for assets used to generate income; the Federal Ministry of Finance's guidance subsequently confirmed the one-year period applies regardless of whether the asset was staked or lent, which removed the single largest complication for anyone using staking services.
Airdrops divide on whether anything was given in return. Received for an action — a task, promotional activity — they are income at receipt. Received passively with no consideration, the position is less settled and depends on the specific circumstances.
Private versus commercial
The whole favourable framework applies to private asset management. Activity that crosses into commercial trading — gewerblicher Handel — leaves it, and the consequences are substantial: trade tax, no one-year exemption, and full business accounting.
There is no bright-line test. The factors that push toward commercial classification are trading on your own account with borrowed capital, operating with an organised business apparatus, acting for third parties, and a scale and frequency that resembles a dealer rather than an investor. Mining at scale and running validators as a business also raise the question directly.
For an individual buying and holding, and trading occasionally, private classification is normal. For someone running high-frequency strategies or a validator operation, this is the first question to resolve with an adviser, not the last.
Records that satisfy the requirement
The one-year rule requires you to prove when each unit was acquired. That is the whole compliance burden, and it is unforgiving where records are missing: without an acquisition date you cannot demonstrate the holding period, and the gain is treated as taxable.
Keep per-transaction records of date, asset, quantity, euro value at the time, fees, and the wallet or venue. Export from exchanges regularly rather than at year end, because access can be lost and history goes with it. Since FIFO is applied per wallet, keeping assets consolidated rather than scattered across a dozen addresses makes the calculation far simpler.
German crypto tax software is well developed and produces reports in a format accountants accept, but treat the output as a draft — DeFi positions, liquid staking tokens and bridged assets are classified inconsistently by every tool.
Reporting
Private sale gains are reported in Anlage SO of the income tax return; income from staking and lending in the appropriate income annex. The tax year is the calendar year, and the filing deadline depends on whether you file yourself or through an adviser.
German exchanges report to the authorities, and the international exchange-of-information frameworks now in force extend that to accounts held abroad. Assume the data exists on the other side, and note that the one-year exemption is a benefit you claim with evidence, not a reason to omit the transactions from the return.
The practical implication
The structure rewards a specific behaviour: buy, hold past the year, and do as little in between as possible. If you intend to hold long term anyway, the German rules make patience directly profitable in a way that jurisdictions with flat capital gains rates do not — and every swap, every rebalance and every card payment is a decision to give that up for that portion of the position. The general principles of tracking cost basis across all of this are in our cost basis guide.
Next step
Understood the mechanics? Keep going, or compare the services.
FAQ
Is crypto tax-free in Germany after one year?
Does staking extend the holding period to ten years?
Does swapping one crypto for another reset the clock?
When does crypto trading become commercial in Germany?
Related guides
All Tax guides →- Crypto Tax in the UK: HMRC Rules for Traders and StakersHMRC treats crypto as property, not currency. That single decision drives the pooling rules, the 30-day rule and why swapping one token for another is a taxable event.Intermediate11 min
- Crypto Taxes 101: What Every Beginner Needs to KnowThe taxable events every new crypto holder needs to track from day one — trades, swaps, staking rewards and more — explained without the jargon.Beginner9 min
- How Automated Market Makers (AMMs) Work Under the HoodNo order book, no market makers standing by — just a formula and a pool of reserves. Here's the mechanics behind the constant-product curve that prices most of DeFi.Intermediate10 min
- Impermanent Loss Explained: The Hidden Risk of Providing LiquidityProviding liquidity looks like free yield until you compare it against simply holding the two assets — the gap between those outcomes is impermanent loss, and it's bigger than most LPs realise.Intermediate11 min